
Yes, most major insurers and Medicare cover TMS insurance coverage claims for treatment-resistant major depressive disorder, but only when specific documentation requirements are met. That is the short answer, and it holds true whether you carry an employer-sponsored plan, a private policy, or Medicare.
The qualifiers matter as much as the yes. You will typically need proof that documentation of failed antidepressant medication trials, a prior authorization on file before treatment starts, and a diagnosis that fits your payer’s covered criteria. OCD coverage is inconsistent from plan to plan, and Medicare tends to restrict approval to severe major depressive disorder specifically.
- Medication-trial documentation is the single biggest approval factor
- Prior authorization must be secured before your first session, not after
- Diagnosis and protocol limits vary by insurer and by state Medicaid program
Pro Tip: Before you assume you’re covered or denied, ask your clinic to run a benefits check. Most TMS providers, including Imindmental, do this at no cost before you commit to a treatment plan.
Key Takeaways
TMS insurance coverage generally depends on documented medication-trial failures, prior authorization, and a diagnosis that meets your payer’s specific severity criteria.
| Point | Details |
|---|---|
| Medicare limits apply | Coverage typically caps at a treatment duration limit of about six weeks and requires a face-to-face psychiatrist evaluation. |
| Documentation drives approval | Two to four failed medication trials with dosage and duration details are usually required. |
| Commercial plans vary | Session approvals commonly range from 30 to 36 depending on your specific plan. |
| Denials are often fixable | Most rejections stem from incomplete records, not true ineligibility, and can be appealed. |
| Imindmental runs benefits checks | Imindmental verifies coverage and submits prior authorization for patients pursuing TMS therapy. |
This article is general information, not a substitute for advice from a qualified doctor. Consult a qualified healthcare professional about your own circumstances before acting on anything here.
Table of Contents
- Which TMS Insurance Coverage Rules Apply to Your Diagnosis?
- What Documentation Do Insurers Require for Approval?
- How Do Medicare, Medicaid, and Commercial Plans Differ?
- What Will TMS Cost You Out of Pocket?
- How Do Prior Authorization and Appeals Actually Work?
- How Do You Verify Your Own TMS Coverage?
- A Practitioner’s View on Insurance and Patient Selection
- How Imindmental Helps You Navigate TMS Coverage
- Sources
Which TMS Insurance Coverage Rules Apply to Your Diagnosis?
Insurers overwhelmingly approve TMS insurance coverage for moderate-to-severe major depressive disorder once you’ve documented failed medication attempts. That is the clearest, most consistent lane through the approval process. Payers rely on evidence reviews showing TMS works for depression that hasn’t responded to standard drug therapy, and clinical evidence summaries back that pattern strongly enough that most major carriers have built it into their standard policy language.
OCD coverage looks different. Some plans cover it under the same general behavioral health provisions; others exclude it outright or require a separate, more stringent review. Newer or off-label TMS protocols, including certain accelerated or theta-burst variations, face the same inconsistency. Mayo Clinic advises patients to confirm their specific coverage before scheduling, precisely because policies diverge this much between carriers.
A common misconception is that the device brand or manufacturer determines coverage. It doesn’t. Insurers care about:
- Your diagnosis code and its documented severity
- Whether the device holds FDA clearance for your indication
- Whether your clinical records satisfy the payer’s specific criteria
The paperwork, not the hardware, decides whether your claim goes through.
What Documentation Do Insurers Require for Approval?
Getting TMS approved comes down to building a clean, complete clinical file before you ever submit a prior authorization request. Insurers are looking for a specific pattern of evidence, and missing even one piece can delay approval by weeks.
- Medication-trial history. You need documentation of at least two, and often up to four, antidepressant trials that failed to produce adequate relief, as explained in the Medication Assisted Therapy – Diamond Wellness resource. Each entry should record the drug name, dose, duration, and reason it was discontinued, whether that’s lack of response or intolerable side effects.
- Accurate diagnostic coding. Your ICD-10 code needs to match the severity level your payer covers, typically moderate-to-severe recurrent MDD.
- Medical exclusion screening. Implanted metal devices, certain pacemakers, and a personal or family seizure history can disqualify you or require additional documentation to proceed safely.
Pro Tip: Ask your psychiatrist’s office for a written medication history summary rather than relying on memory. A documented timeline moves faster through insurer review than a verbal recollection ever will.
If you’re still working with your psychiatrist to establish that treatment history, a psychiatric evaluation is usually the starting point before TMS becomes an option.
How Do Medicare, Medicaid, and Commercial Plans Differ?
Medicare, Medicaid, and commercial insurance each apply distinct rules to TMS insurance coverage, and knowing which bucket you fall into changes what you should expect.
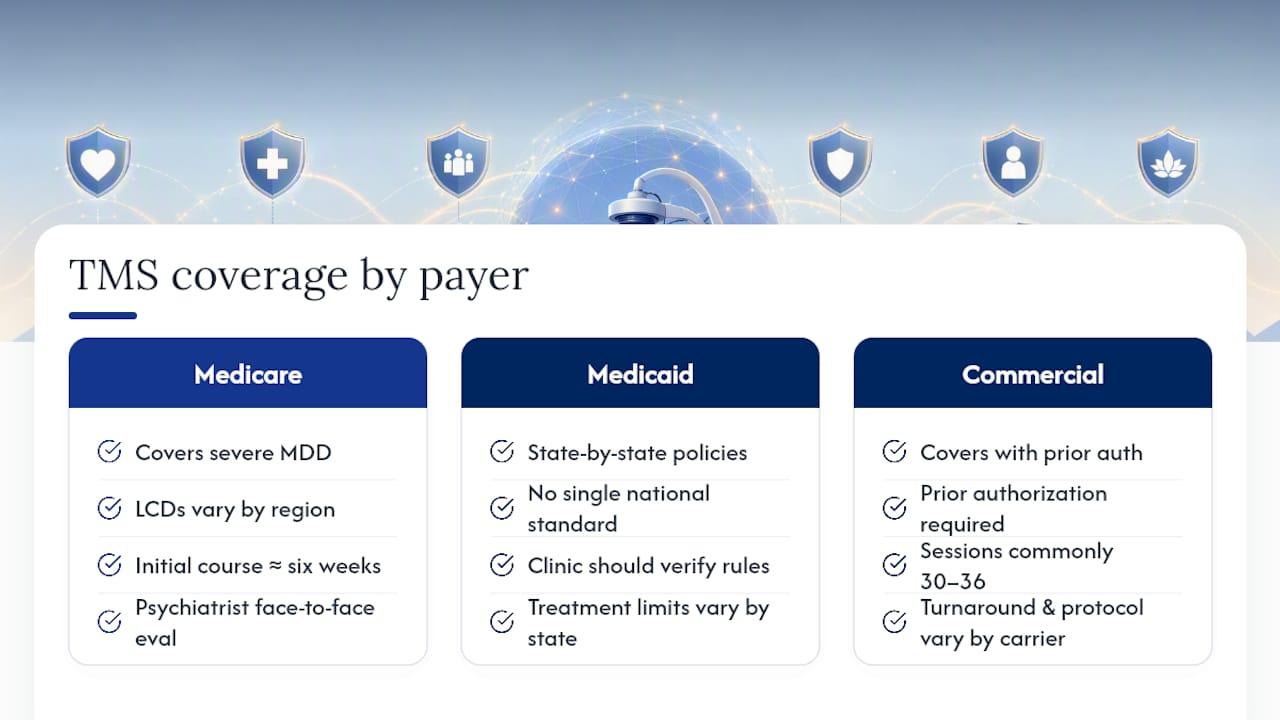
Medicare covers TMS for severe major depressive disorder, but coverage is shaped by Local Coverage Determinations that vary by region. The CMS LCD for TMS spells out strict clinical criteria, and Medicare’s own guidance generally limits an initial course to about a treatment duration limit of about six weeks, with a psychiatrist’s face-to-face evaluation required beforehand.
Medicaid policies differ state by state. There’s no single national standard, so the smartest move is asking your clinic to verify your specific state’s Medicaid rules rather than assuming coverage mirrors Medicare’s.
Commercial plans tend to be more flexible once prior authorization clears. Session approvals commonly land in the 30 to 36 session range, though prior-auth turnaround time and specific protocol restrictions still vary by carrier.
What Will TMS Cost You Out of Pocket?
Your actual cost depends heavily on where you are in your deductible and what coinsurance your plan assigns to outpatient procedures. Medicare beneficiaries may face coinsurance after meeting their deductible, and Medicare Advantage plans generally mirror Original Medicare’s cost-sharing structure with some plan-specific variation.
If your insurer denies coverage or you’re uninsured, per-session self-pay rates for TMS commonly range from roughly $200 to $500, and a full course runs 20 to 36 sessions.
- HSA and FSA funds are generally eligible for TMS, which softens the financial hit considerably
- Many clinics offer payment plans or third-party financing when insurance denies coverage
- Repeat or maintenance courses may require a fresh prior authorization even if your first round was approved
How Do Prior Authorization and Appeals Actually Work?
Getting TMS authorized starts with your clinic submitting a benefits verification request, then a formal prior-authorization packet once your eligibility looks solid.
- Benefits check. Your clinic contacts your insurer to confirm TMS is a covered benefit under your specific plan and to identify any prerequisites.
- Prior authorization submission. Your clinic submits medication history, diagnostic codes, and psychiatric evaluation notes for review. Healthcare defines this step as insurer approval required before a service qualifies for payment.
- Denial response, if needed. Common denial reasons include insufficient medication-trial documentation or a diagnosis code that doesn’t match covered severity levels.
- Appeal filing. Your psychiatrist can submit a letter of medical necessity along with supplemental records addressing the specific denial reason.
Pro Tip: Clinics that keep thorough, well-organized medication and diagnostic records tend to see faster approvals and fewer denials, since most rejections trace back to incomplete documentation rather than actual ineligibility.
How Do You Verify Your Own TMS Coverage?
Before you schedule anything, get direct answers from your insurer.
- Call your insurer and ask: Is prior authorization required for TMS? Which ICD-10 codes do you accept for approval? Is there a session limit? Are specific devices or protocols excluded?
- Gather your records: your diagnosis history, a complete medication-trial list with doses and durations, and your psychiatrist’s contact information.
- Ask your clinic to verify benefits directly. Providers offering TMS therapy can run this check on your behalf and submit prior authorization once your documentation is complete.
Pro Tip: Request written confirmation of your benefits check, not just a verbal summary. It becomes useful if a claim is later disputed.
A Practitioner’s View on Insurance and Patient Selection
TMS eligibility criteria exist for good reason. They push patients through appropriate medication trials first, which protects you from an invasive-sounding procedure you may not need yet. What I find frustrating, working alongside psychiatric teams, is how often good candidates get stuck not because they’re ineligible, but because nobody organized their medication history clearly enough for an insurer to say yes quickly. Solid documentation and a collaborative conversation with your psychiatrist solve more coverage problems than any appeal letter does.
How Imindmental Helps You Navigate TMS Coverage
Imindmental runs benefits checks and submits prior authorization on your behalf, so you’re not deciphering insurer language alone or guessing whether your documentation is complete. Our team at Deep TMS Therapy works directly with your psychiatric evaluation and medication history to build the file your insurer needs to say yes.
If your plan requires a fresh psychiatric evaluation before authorization, our psychiatry services can establish that documentation as part of your treatment plan. And if coverage comes back partial or denied, we’ll walk you through HSA and FSA eligibility and self-pay options so a coverage gap doesn’t become a treatment gap. Reach out to schedule a benefits-check appointment and find out exactly where you stand.
Sources
- CMS — LCD: Transcranial Magnetic Stimulation (TMS) in the Treatment of Adults with Major Depressive Disorder (L34998)
- TMS Insurance Coverage Guide | Medicare, BCBS, Aetna, Cigna & More
- Mayo Clinic — Transcranial magnetic stimulation

